Investment management
Portfolios
A portfolio that seeks better risk-adjusted returns, whether markets rise or fall.
Uncorrelated quantitative strategies, in an account in the client's name at Interactive Brokers.
- The client's account at Interactive Brokers
- Every order checked against written limits
- From USD 20,000, withdrawals at any time
Athena replies by email to arrange a meeting.
The portfolio fluctuates less than any individual strategy
The strategies have low or negative correlation with each other: their good and bad days seldom coincide.
Annual volatility
- Strategy A
- 8.3%
- Strategy B
- 9.4%
- Strategy C
- 11.9%
- Strategy D
- 8.8%
- Portfolio
- 5.2%
Daily change in the portfolio and each strategy (%)
Strategy A
Strategy B
Strategy C
Strategy D
Portfolio
One quarter in each strategy
Simulated data: four strategies over three years; bars for 100 of those days. Pairwise correlations from −0.03 to +0.17.
How one earns, not just where.
Almost everything one owns earns when markets rise. In 2022, global stocks and bonds fell in the same year.
Portfolios adds to what one already owns.
Stocks and bonds in 2022 →How the portfolio is built
The portfolio is designed to gain along a steadier path.
Strategies that gain on their own.
Each is designed to gain from its own factors and market regimes, so combining them doesn’t dilute the return.
That don’t move together.
Responding to their own factors, their correlation is low or negative. That diversification makes the portfolio swing less than each strategy alone.
Weighted as one portfolio.
Each strategy’s weight is optimized for the portfolio as a whole and set to the target volatility the client chooses.
Returns average out; falls don’t.
Cumulative change
Fall from the previous high
| Strategy | Return above Treasury bills (3 years) | Annual volatility | Largest fall | Sharpe |
|---|---|---|---|---|
| A | +16.2% | 8.3% | −10.7% | 0.65 |
| B | +17.1% | 9.4% | −16.6% | 0.61 |
| C | +16.7% | 11.9% | −25.4% | 0.47 |
| D | +14.7% | 8.8% | −9.6% | 0.56 |
| Portfolio | +16.2% | 5.2% | −5.0% | 1.03 |
Strategies: trend, reversion, relative value and carry, global macro, long and short volatility.
Method: quantitative models and techniques; discretionary decisions draw on quantitative analysis.
Each type of strategy gains in its own conditions.
Examples with historical prices
Textbook examples with historical prices, each in a year with the conditions in which that type gains: how it gains and when it loses. Hypothetical trades and results, before costs. These are not Athena’s positions or models.
Buys Apple when it closes above its 15-session average and returns to cash when it closes below.
Apple (AAPL)
Account value
137.45Year starts at 100 · at the Dec 31 close
Deepest decline of the year: −12.10%, from the Apr 23 high to the Jun 7 low. It regained that high on Sep 22.
Assumptions and data
The example invests the whole account in Apple or holds cash. It evaluates the signal at the close and trades at the next session’s open.
The account starts at 100. Each position is valued at the daily close, including dividends received or owed on the ex-dividend date. Fees, slippage, interest and stock borrowing costs are excluded and can change a gain into a loss. Zooming preserves the account’s earlier history.
Risk, a written decision
The client chooses the risk level before investing.
- Level 16%target volatilityBad year (illustration)−12% or more
- Level 29%target volatilityBad year (illustration)−18% or more
- Level 312%target volatilityBad year (illustration)−24% or more
At a limit, any order that would add risk is blocked and the client is notified within 24 hours.
Target volatility measures how much the account moves, not what it earns. The signed mandate applies.
Limiting falls matters: the deeper the fall, the harder the way back.
How risk is managed along the way
The models seek to detect when the market changes.
Regimes
Method: a hidden Markov model estimates the probability of calm or stress.
Market regimes (HMM)
| From \ To | Calm | Stress | Persistence |
|---|---|---|---|
| Calm | 0.986 | 0.014 | Mean duration: 71 days |
| Stress | 0.035 | 0.965 | Mean duration: 29 days |
The allocation adjusts gradually as the probability of each regime changes, within the mandate’s limits.
Smoother, but later · No actual weights or thresholds
- Calm: low volatility
- Stress: high volatility
- Probability of stress
- Gradual adjustment
- Binary switch (illustrative)
The model infers the regime using only the data available at each date, so it recognises shifts with some lag.
Diversifying reduces risk without removing it: under stress, correlations rise.
Correlations
Method: four simulated strategies, with their correlations in calm and under stress.
Correlations, in calm and under stress
Weekly returns
63-day rolling volatility
| A | B | C | D | |
|---|---|---|---|---|
| A | 1 | 0.0 | −0.1 | 0.1 |
| B | 0.0 | 1 | −0.1 | −0.1 |
| C | −0.1 | −0.1 | 1 | 0.1 |
| D | 0.1 | −0.1 | 0.1 | 1 |
| A | B | C | D | |
|---|---|---|---|---|
| A | 1 | 0.3 | 0.3 | 0.5 |
| B | 0.3 | 1 | 0.2 | 0.3 |
| C | 0.3 | 0.2 | 1 | 0.5 |
| D | 0.5 | 0.3 | 0.5 | 1 |
- Strategies A–D
- Portfolio
- Stress
Under stress, the benefit of diversifying shrinks. In Portfolios, the client chooses the target-volatility level (6%, 9% or 12%).
When markets turn rough, exposure comes down.
Target volatility
Method: if estimated volatility rises, exposure is cut in proportion.
Target volatility
- Unscaled
- With target volatility
- Target (illustrative)
- Cap: 1.5×
Volatility nears the target without being pinned to it: a sudden shock lands at the previous day's exposure.
Exposure to the worst days is measured and limited.
VaR and CVaR
Method: with the same variance, fat tails can share the VaR and lose more. CVaR is the average loss on the days beyond the VaR.
VaR and CVaR
- Normal
- Student’s t (4), same variance
- Average loss beyond the VaR
VaR marks a threshold, not a maximum loss: beyond it, fat tails lose more.
Control before acting
Every order is checked against the mandate's limits before it is sent.
Decision or model
Systematic or discretionary
Automatic check
Against the mandate's written limits
Interactive Brokers
The order reaches the client's account
Daily reconciliation
Athena's records, matched to the broker's
With Athena QS Console, Athena's own software, which operates with real capital.
See the method →Who it is for
A part of one's wealth that doesn't depend on bull markets.
- Already invests and wants part of their wealth to earn differently.
- Can hold it for five years or more: a suggested horizon, not a lock-up.
- Accepts the swings of the risk level they choose.
Everything checkable
The account is the client's. Everything is in view.
Who can move what
Athena
Athena sends orders, within the limits of the mandate
Athena receives only its fee, through the broker
Account in the client's name, at Interactive Brokers, which holds it
Withdrawals only go to accounts in the client's name
Client
The client's money never passes through Athena.
The mandate can be revoked at any time.
- Every month
- The result after fees and costs, alongside T-bills.
- Every quarter
- Five tests with written thresholds:
- That the strategies remain uncorrelated with each other.
- That each behaves as designed.
- That the systematic ones operate according to their models.
- That none weighs or costs too much in its market.
- That combining them is still worth its cost.
- Every year
- A review of the risk level and limits.
Who decides
On a bank desk, earning when markets fall is part of the job.
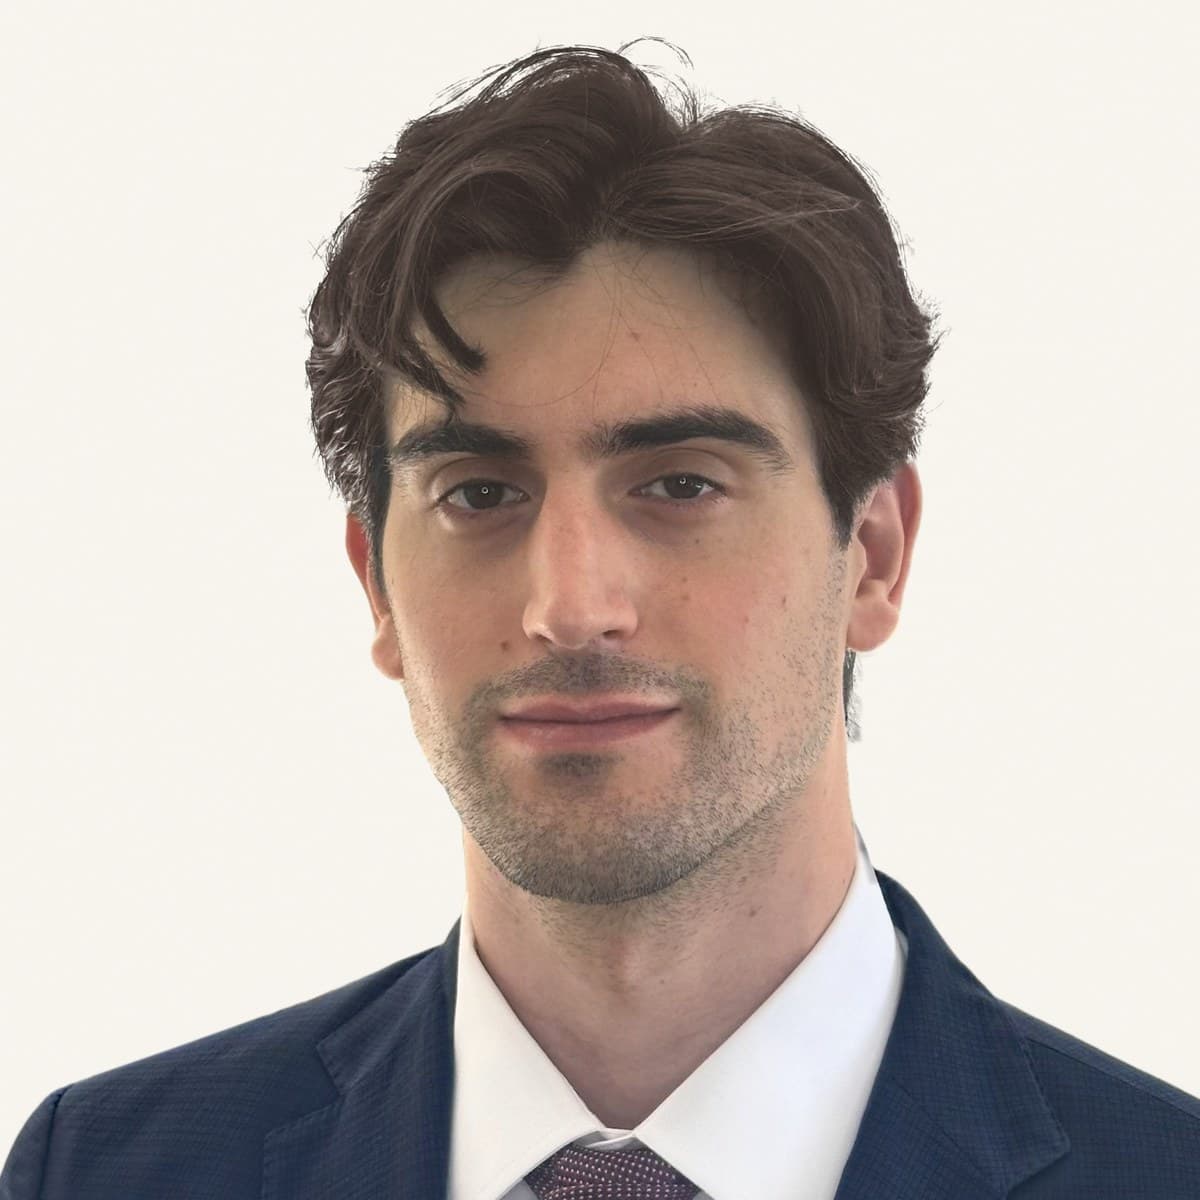
Luciano Fabbri Soto-Aguilar
Chief Investment Officer
CQF · Industrial engineer
Banco de Chile
Treasury desk: derivatives.
Bci
Market and liquidity risk models, and stress tests.
Itaú
International rates and currencies trader.
Athena
Founder and Chief Investment Officer.
«A strategy without an invalidation criterion is not a strategy. It is an opinion with capital behind it.»More about Athena →
Key facts
The terms, at a glance.
USD 20,000
minimum; the account is measured and reported in US dollars
6%, 9% or 12%
target volatility, chosen by the client
1.785%
a year for management (1.5% + VAT)
23.8%
for performance (20% + VAT)
- The account
- In the client's name at Interactive Brokers, which holds it in custody. Withdrawals go only to the client's own accounts.
- Who signs
- Athena Quantitative Strategies SpA.
- Exit
- No lock-up and no exit fee; the mandate can be revoked at any time.
- Risk
- Each level has written limits on loss, margin and leverage. See the levels ↑
- CMF
- Athena Quantitative Strategies is not registered in the CMF's Register of Portfolio Managers and is not supervised by it.
Fees
Performance is charged only on gains above the previous high plus the T-bill rate. Broker costs are separate.
Worked example: USD 50,000, T-bills at 4%, before broker costs.
| Before fees | Athena's fees, VAT included | Of which, performance |
|---|---|---|
| A year of +10% | USD 1,415 | USD 482 |
| A year of −8% | USD 846 | no performance fee |
| The following year, at +12% | USD 851 | no performance fee |
A single layer of fees, deducted in plain view in the account statement.
How to start
From the first message to the account, in four steps.
First contact
A first message to Athena, answered by email.
Meeting
One hour, in person or by video; advisers may join.
Proposal and mandate
In writing: risk level, limits and how each is checked.
Account and reporting
In the client's name at Interactive Brokers; monthly reports.
This page describes the service and its terms; the written mandate governs each relationship. All investment involves risk, including loss of capital. See the risks of investing →